

 1-888-601-9980

Compare the Best Visitor Insurance Plans in Canada
Apply online and save BIG
 CONNECT ON WHATSAPP




Trusted by Canadians


What is visitor to Canada insurance?
Visitor insurance Canada is an emergency medical coverage for non-residents visiting Canada, including parents on Super Visas, tourists, international students, and foreign workers. Policies start at $70–$115/month for healthy travelers under 65, with minimum $100,000 coverage.
What does visitor insurance cover?
Visitor insurance for Canada helps cover eligible emergency medical expenses if a non-resident becomes unexpectedly ill or injured during their stay. Depending on the plan, coverage may include emergency hospital and physician care, diagnostic tests, prescription drugs, ambulance transportation, emergency dental treatment and medical evacuation.
Coverage is subject to the policy’s limits, deductible, exclusions and eligibility requirements. Here’s a list of all the inclusions in a medical insurance plan for visitors to Canada:
- Emergency medical and hospital care: Covers reasonable and customary charges for medical care received from a physician, whether in or out of the hospital
- Prescription drugs: Covers medically necessary prescription medication required to treat an eligible emergency, up to the plan limit
- Diagnostic tests: Covers necessary blood work, X-rays, CT scans, MRIs and other tests used to diagnose or treat an emergency
- Paramedical services: Covers services such as physiotherapy, chiropractic care or massage therapy, where medically necessary and allowed by the policy
- Pre-existing conditions: May cover stable pre-existing conditions. Coverage depends on the insurer’s stability period, medical questionnaire and policy wording
- Repatriation: Cover the costs of emergency medical evacuation back to your home country, which can be a significant cost without coverage
- Accidental death and dismemberment (AD&D): May provide a lump-sum benefit for a covered accidental death or qualifying loss of limb, sight, speech or hearing
- Emergency dental care: May provide coverage for emergency dental treatment or surgery that may have resulted from an accident or sudden injury
- Ambulance transportation: Covers the costs of ambulance services (whether ground or air) needed to transport the visitor to the nearest hospital or medical facility
- Meals, accommodation and local transportation: May cover eligible hotel, meal and taxi costs if a covered emergency delays the visitor’s return home
- Childcare: Certain plans may cover limited childcare expenses if the insured visitor is hospitalized and unable to care for their dependent child
- Side trips or trip breaks: May allow limited travel outside Canada or a short return to the visitor’s home country without ending coverage
Who needs visitor insurance in Canada?
Visitor insurance is recommended for tourists, visiting family members, parents and grandparents, international students, and new workers who are not yet covered by a provincial health plan. It is mandatory for Super Visa applicants, who must show qualifying private medical coverage when applying.
Super Visa Insurance
Coverage that fits the requirements for those applying for a Canadian Super Visa
International Students
Coverage for international students attending school in Canada or Canadians studying abroad
Foreign Workers
Coverage for those working in Canada before they are eligible for provincial health plans
Recognized as a leader in the industry

What is super visa insurance?
Super Visa insurance is private emergency medical insurance for parents and grandparents applying for Canada’s Super Visa. It helps cover eligible emergency health-care costs, hospitalization and repatriation because Super Visa holders are not eligible for provincial health coverage.
Because a Super Visa grants long-term, multi-entry access, allowing parents and grandparents to stay in Canada for up to 5 consecutive years per entry, the Canadian government has strict rules in place to ensure these visitors are medically protected.
Super visa insurance requirements
To be approved for a Super Visa, the insurance policy submitted with the application must meet the following strict government criteria:
- Minimum Coverage: The policy must provide at least $100,000 CAD in emergency medical coverage.
- Validity Period: It must be valid for a minimum of 1 year (365 days) starting from the date of entry into Canada.
- Approved Provider: The policy must be issued by a Canadian insurance company or an OSFI-authorized foreign insurer.
- Scope of Coverage: The insurance must specifically cover emergency health care, hospitalization, and repatriation.
- Proof of Payment: You must provide proof that the policy is active and paid for. Insurance quotes alone are not accepted, though policies paid via approved monthly installments are permitted.
- Expanded Care: Policies must also cover emergency mental health treatments, rehabilitation services, and telemedicine consultations.
- Streamlined Claims: Streamlined pre-authorization rules help visitors have their claims approved much faster during an emergency.
How much does visitor insurance to Canada cost?
Super Visa insurance is private emergency medical insurance for parents and grandparents applying for Canada’s Super Visa. It helps cover eligible emergency health-care costs, hospitalization and repatriation because Super Visa holders are not eligible for provincial health coverage.
Because a Super Visa grants long-term, multi-entry access, allowing parents and grandparents to stay in Canada for up to 5 consecutive years per entry, the Canadian government has strict rules in place to ensure these visitors are medically protected.
Super visa insurance requirements
To be approved for a Super Visa, the insurance policy submitted with the application must meet the following strict government criteria:
- Minimum Coverage: The policy must provide at least $100,000 CAD in emergency medical coverage.
- Validity Period: It must be valid for a minimum of 1 year (365 days) starting from the date of entry into Canada.
- Approved Provider: The policy must be issued by a Canadian insurance company or an OSFI-authorized foreign insurer.
- Scope of Coverage: The insurance must specifically cover emergency health care, hospitalization, and repatriation.
- Proof of Payment: You must provide proof that the policy is active and paid for. Insurance quotes alone are not accepted, though policies paid via approved monthly installments are permitted.
- Expanded Care: Policies must also cover emergency mental health treatments, rehabilitation services, and telemedicine consultations.
- Streamlined Claims: Streamlined pre-authorization rules help visitors have their claims approved much faster during an emergency.

Looking for affordable visitor insurance?
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.
What are the types of medical insurance for visitors in Canada?
Explore comprehensive visitor medical insurance options for visiting parents, friends, family, students, and foreign workers.
Visitors to Canada
Canada’s robust public healthcare system does not extend to non-residents of the country. Those visiting Canada from outside the country also need visitor medical insurance to cover the expensive costs of a doctor’s visit, emergency care, prescription, and more if you fall ill during your trip.
Super visa insurance
Canadian citizens and permanent residents can get a super visa for their parents and grandparents to visit them in Canada for as long as two years. A mandatory stipulation of super visa approval is holding a medical insurance policy to cover illnesses or accidents that can occur during this trip
International Students
International students often need emergency health insurance in whichever country they are studying in. This includes both Canadians studying abroad and students completing their education in Canada. Emergency visitor medical insurance ensures one can focus on their studies knowing they won’t have to deal with an unforeseen medical bill.
Foreign Workers
Foreign workers visiting Canada for temporary or permanent employment will not have immediate access to public healthcare. Visitor medical insurance will cover them if they get sick or injured while working in Canada.
Travelling Canadians
Residents of Canada need travel insurance for trips abroad. While your public healthcare or group health insurance covers medical emergencies at home, an accident or medical emergency while you are out of the country can be very costly.
Snowbirds
Snowbirds are retired Canadians who spend the winter season abroad to avoid Canada’s colder months. As a snowbird, it’s important to make sure you have the right travel insurance in place before you head south for the winter, as you will not qualify for public health insurance at your destination.
How much does visitor insurance to Canada cost?
The average cost of visitor health insurance for travelers to Canada typically ranges from $70 to $400 per month. For instance, younger travelers (under 35 years) may pay between $70 and $90 monthly, while those aged 70 years and older may see costs rise between $200 and $400 per month.
The following table shows a comparison of visitor insurance in Canada monthly premiums, with and without pre-existing condition coverage:
| Visitor’s age | Premiums without pre-ex |
Premiums with Pre-ex |
| 25 years | $72.30/mo. | $92.70/mo. |
| 35 years | $90.90/mo. | $100.20/mo. |
| 45 years | $101.70/mo. | $115.50/mo. |
| 55 years | $110.70/mo. | $129.60/mo. |
| 65 years | $133.20/mo. | $168.60/mo. |
| 75 years | $240.00/mo. | $328.80/mo. |
| 85 years | $405.00/mo. | $453.92/mo. |
Why should you buy visitor insurance to Canada?
Visitors to Canada need medical insurance because public healthcare doesn’t cover non-residents visiting Canada. Without insurance coverage, you could face tremendously high costs for medical emergencies. Even your home country’s public health care generally won’t cover trips abroad. The Government of Canada advises comprehensive travel insurance to avoid unexpected expenses for emergency room visits, transportation back to your home country, prescription drug and dental costs.
The following table shows a comparison of visitor insurance in Canada monthly premiums, with and without pre-existing condition coverage:
| Visitor’s age | Premiums without pre-ex |
Premiums with Pre-ex |
| 25 years | $72.30/mo. | $92.70/mo. |
| 35 years | $90.90/mo. | $100.20/mo. |
| 45 years | $101.70/mo. | $115.50/mo. |
| 55 years | $110.70/mo. | $129.60/mo. |
| 65 years | $133.20/mo. | $168.60/mo. |
| 75 years | $240.00/mo. | $328.80/mo. |
| 85 years | $405.00/mo. | $453.92/mo. |

Which company offers the best health insurance plans for visitors to Canada?
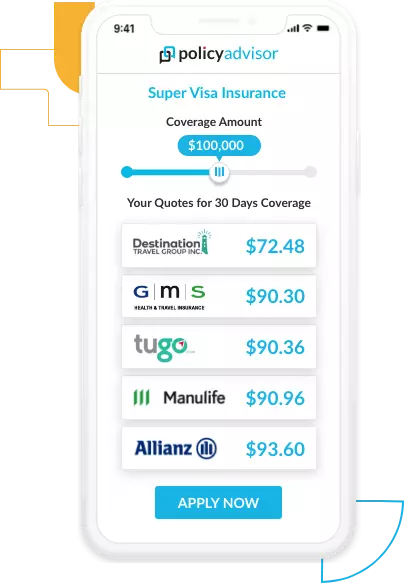
Several insurance providers such as Manulife, Tugo, Allianz, Travelance, 21st century, GMS and more offer health insurance for visitors to Canada. Different providers have different premiums, policy inclusions, deductibles, and coverages.
Some companies offer tiered visitor insurance plans, categorized as basic, standard, and enhanced or Plan A and Plan B. The different plan categories will be priced differently depending on the policy coverage.
At PolicyAdvisor, we partner with Canada’s best visitor insurance providers.
Choose a plan from Canada’s top insurance providers:
- Manulife
- Tugo (iA Financial Group)
- Group Medical Services (GMS)
- Allianz
- 21st Century Travel Insurance Limited
- Destination Canada
- Travelance
- Secure Travel



Why should you buy visitor insurance to Canada?
Visitors to Canada need medical insurance because public healthcare doesn’t cover non-residents visiting Canada. Without insurance coverage, you could face tremendously high costs for medical emergencies. The Government of Canada advises comprehensive travel insurance to avoid unexpected expenses.
An emergency visit to the hospital can cost anywhere between $1,000 – $1,200 for non-residents. MRIs can cost $1,500 or more, and a 24 hour stay in the hospital can cost $3,000 to $6,000. Without insurance, visitors could face significant out-of-pocket expenses for medical emergencies, hospitalization, or even routine care.
You need visitor insurance in Canada because:
- You are not covered under Canada’s public healthcare plans
- Treatment for medical emergencies and prescriptions are expensive and may require cash payments
- Your home country’s public health care offering generally does not cover trips abroad
- Medical insurance for visitors to Canada can cover a broad range of potential situations, including emergency room visits, transportation back to your home country, and prescription drug and dental costs
Frequently asked questions

- Non-emergency treatments
- Routine check-ups and preventive care
- Pregnancy-related care (unless emergency)
- Mental health treatment (except emergency - NEW coverage in 2025)
- High-risk activities without additional coverage
- Treatment related to alcohol or drug abuse
- Cosmetic procedures
- Some provinces provide health coverage after waiting periods
- Others require students to purchase private coverage
- Many schools require proof of insurance for enrollment
- Student insurance often includes mental health and sports coverage
